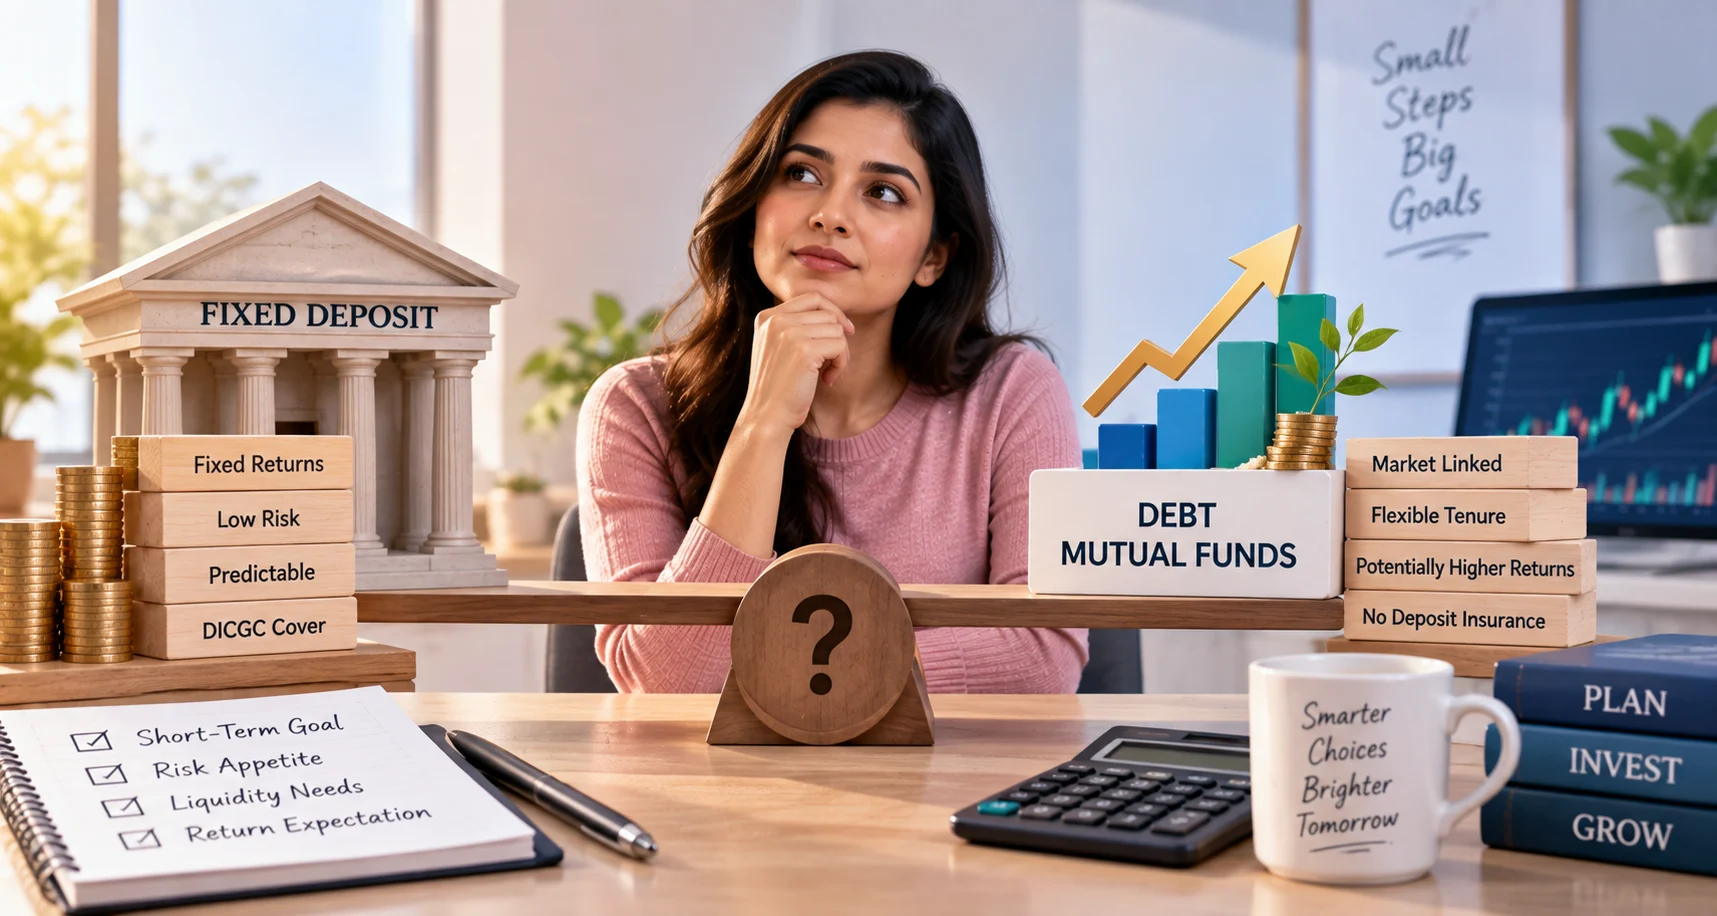
When choosing a short-term investment, many investors compare a fixed deposit vs debt mutual fund because both options focus on fixed-income assets and can be used for goals such as emergency savings, planned expenses, or parking surplus money.
However, they work differently. A fixed deposit offers a predetermined interest rate for a selected tenure, while a debt mutual fund invests in debt and money-market securities and its value can change with market conditions.
Understanding the difference between a fixed deposit vs debt mutual fund can help you select an option based on your time horizon, risk tolerance, liquidity needs, and return expectations.
What Is a Fixed Deposit?
A fixed deposit is a bank deposit where you invest a lump sum for a predetermined period at an agreed interest rate.
At maturity, you generally receive the principal along with the applicable interest. Depending on the bank and FD type, interest may be paid monthly, quarterly, annually, or at maturity.
The main attraction of an FD is predictability. If you choose a fixed rate, you generally know the interest rate applicable to the deposit when you book it.
Bank deposits, including fixed deposits, are covered by DICGC deposit insurance up to ₹5 lakh per depositor per bank, including principal and accrued interest, subject to the applicable rules.
What Is a Debt Mutual Fund?
A debt mutual fund invests in instruments such as government securities, corporate bonds, certificates of deposit, commercial paper, and other money-market or fixed-income instruments, depending on the scheme.
Unlike an FD, a debt mutual fund does not promise a fixed return. Its NAV can move based on interest rates, credit quality, liquidity, and changes in the value of securities held by the scheme.
SEBI requires mutual fund schemes to display a Riskometer so investors can understand the broad risk level of a scheme.
This is an important distinction when comparing a fixed deposit vs debt mutual fund.
Fixed Deposit vs Debt Mutual Fund: Key Differences
| Feature | Fixed Deposit | Debt Mutual Fund |
|---|---|---|
| Return | Predetermined interest rate | Market-linked return |
| Principal value | Does not fluctuate like a mutual fund NAV | NAV can rise or fall |
| Risk | Relatively predictable, subject to bank and deposit risk | Interest-rate, credit and liquidity risks |
| Tenure | Selected upfront | Usually open-ended, depending on scheme |
| Liquidity | Premature withdrawal may involve conditions or penalties | Units can generally be redeemed, subject to scheme rules |
| Deposit insurance | Eligible bank deposits covered up to ₹5 lakh under DICGC rules | Not covered by DICGC |
| Return certainty | Higher predictability | No guaranteed return |
| Investment structure | Bank deposit | Market-linked investment |
| Suitable for | Investors prioritising predictable returns | Investors comfortable with market-linked debt investments |
The comparison shows why there is no universal answer when evaluating a fixed deposit vs debt mutual fund.
Fixed Deposit vs Debt Mutual Fund for Short-Term Goals
For a short-term goal, the first question should be when you need the money.
If you know that you will need a specific amount on a particular date and want greater certainty around the maturity value, an FD can provide a straightforward structure.
For example, suppose you need money after two years for a planned expense. You could select an FD tenure close to your target date and know the applicable interest rate when you book it.
A debt mutual fund can provide more flexibility in some situations because many schemes allow investors to redeem units before the intended holding period. However, the redemption value can be different from the amount originally invested.
Therefore, the fixed deposit vs debt mutual fund decision should consider both the goal date and the amount of risk you can accept.
Return Comparison
One of the biggest differences between an fixed deposit vs debt mutual fund is how returns are generated.
With an FD, the interest rate is agreed upon when the deposit is opened. The actual return is therefore easier to estimate.
Debt mutual fund returns depend on the performance of the securities held by the scheme. Changes in market interest rates can affect bond prices and therefore the NAV. SEBI materials also identify interest-rate, credit and liquidity risks in debt investments.
A debt fund may therefore generate a positive return, but the return is not fixed in the same way as an FD.
Risk: Fixed Deposit vs Debt Mutual Fund
Risk is another major factor in the fixed deposit vs debt mutual fund comparison.
An FD does not have daily market-price fluctuations like a mutual fund. However, it is still important to consider the financial strength of the bank and the applicable deposit insurance framework.
DICGC currently provides insurance of up to ₹5 lakh for eligible deposits held in the same right and same capacity at an insured bank. Deposits across different banks can receive separate insurance coverage subject to the rules.
Debt mutual funds carry investment risks. A debt security can lose value because of changes in interest rates, deterioration in the issuer’s credit quality, or liquidity conditions.
Therefore, debt mutual funds should not be treated as risk-free alternatives to FDs.
Liquidity and Premature Withdrawal
Liquidity can influence the fixed deposit vs debt mutual fund decision.
An FD is usually created for a specific tenure. Banks may allow premature withdrawal, but the applicable interest rate, penalty, and terms depend on the bank and deposit product.
Debt mutual funds are generally open-ended unless the scheme has a different structure. Investors can normally redeem units according to the scheme’s rules, but the amount received depends on the prevailing NAV and applicable charges or exit load, if any.
This means a debt fund may offer flexibility without guaranteeing the value you will receive at redemption.
Tax Considerations
Tax treatment is an important part of the fixed deposit vs debt mutual fund comparison.
FD interest is taxable according to the applicable income-tax rules. Depending on the interest amount and taxpayer circumstances, banks may also deduct TDS where applicable.
Debt mutual fund taxation depends on the type of scheme, date of acquisition, holding period, and prevailing tax rules. Investors should check the current tax treatment before investing because mutual fund taxation can change through amendments to tax laws.
Do not compare investments only on their headline return. Compare the expected post-tax outcome as well.
When Can an FD Make Sense?
An FD may be considered when you:
- Prefer predictable interest rates
- Have a clearly defined investment period
- Want a simple investment product
- Do not want daily NAV fluctuations
- Need a known maturity structure
- Prioritise capital stability over market-linked returns
For investors who value certainty, an FD can be easier to understand and plan around.
When Can a Debt Mutual Fund Make Sense?
A debt mutual fund may be considered when you:
- Are comfortable with market-linked returns
- Understand debt-market risks
- Want access to different debt fund categories
- Need potentially greater flexibility than a fixed-tenure deposit
- Are willing to monitor the scheme’s risk profile and portfolio
However, investors should read the scheme documents and Riskometer before investing. SEBI’s framework highlights that debt funds can carry different levels of interest-rate and credit risk.
Fixed Deposit vs Debt Mutual Fund: Example
Suppose you have ₹5 lakh that you expect to need after two years.
With an FD, you can select a two-year deposit and know the applicable interest rate at the time of booking. Your maturity value can be estimated using the bank’s stated interest and compounding method.
With a debt mutual fund, the ₹5 lakh is invested in units. The value after two years depends on the NAV when you redeem the investment. It could be higher or lower depending on market conditions and the performance of the underlying securities.
This example highlights the central difference in the fixed deposit vs debt mutual fund decision: predictable deposit interest versus market-linked investment performance.
Fixed Deposit vs Debt Mutual Fund: What Should You Compare?
Before selecting either option, compare:
- Investment period: How long can you keep the money invested?
- Return expectation: Do you need a predictable return?
- Risk tolerance: Can you accept NAV fluctuations?
- Liquidity: How quickly might you need the money?
- Tax impact: What will you receive after tax?
- Capital protection: How important is principal stability?
- Investment objective: Is the money for a fixed future expense or flexible savings?
These factors provide a more useful framework than simply comparing advertised interest rates or past fund returns.
FAQs
Is a fixed deposit safer than a debt mutual fund?
An FD does not have the market-linked NAV fluctuations of a debt mutual fund. Eligible bank deposits also have DICGC insurance up to ₹5 lakh per depositor per bank under the applicable rules. Debt mutual funds are market-linked and carry investment risks.
Can a debt mutual fund guarantee returns?
No. Debt mutual fund returns are not guaranteed. Their NAV can change because of interest-rate movements, credit events, liquidity conditions, and the performance of the securities in the portfolio.
Is an FD better for a short-term goal?
An FD can be suitable when you want a predictable interest rate and have a clearly defined investment period. The suitability depends on your goal, liquidity requirements, tax position, and risk tolerance.
Do debt mutual funds have risk?
Yes. Debt mutual funds can have interest-rate, credit, liquidity, and market-related risks. SEBI’s Riskometer helps investors understand the broad risk level of a mutual fund scheme.
Is the return from an FD fixed?
The interest rate applicable to an FD is generally predetermined when the deposit is booked. The final amount can depend on the deposit amount, tenure, interest rate, compounding frequency, and applicable terms.
Key Takeaway
The fixed deposit vs debt mutual fund decision depends on what you want from your money.
An FD focuses on predictable interest and a defined maturity structure, while a debt mutual fund provides market-linked exposure to debt securities with different levels of risk.
If your priority is knowing the applicable interest rate and having a straightforward maturity structure, an FD may fit your objective. If you are comfortable with market-linked returns and understand debt-market risks, a debt mutual fund may be worth considering.
Instead of asking which option is universally better, compare the fixed deposit vs debt mutual fund based on your investment horizon, liquidity needs, tax position, and risk tolerance.
